
Your will does not control everything
If you've ever asked yourself, "Should I name a beneficiary or use my will in Canada?", you're asking exactly the right question, and the answer matters more than most people realize. Many Canadians assume their will is the master document. The one that controls everything. The one their family will follow when the time comes. But for a large portion of the assets Canadians actually hold, including RRSPs, TFSAs, and life insurance, a separate form filed with a financial institution is what actually decides who gets paid, how fast, and how much.
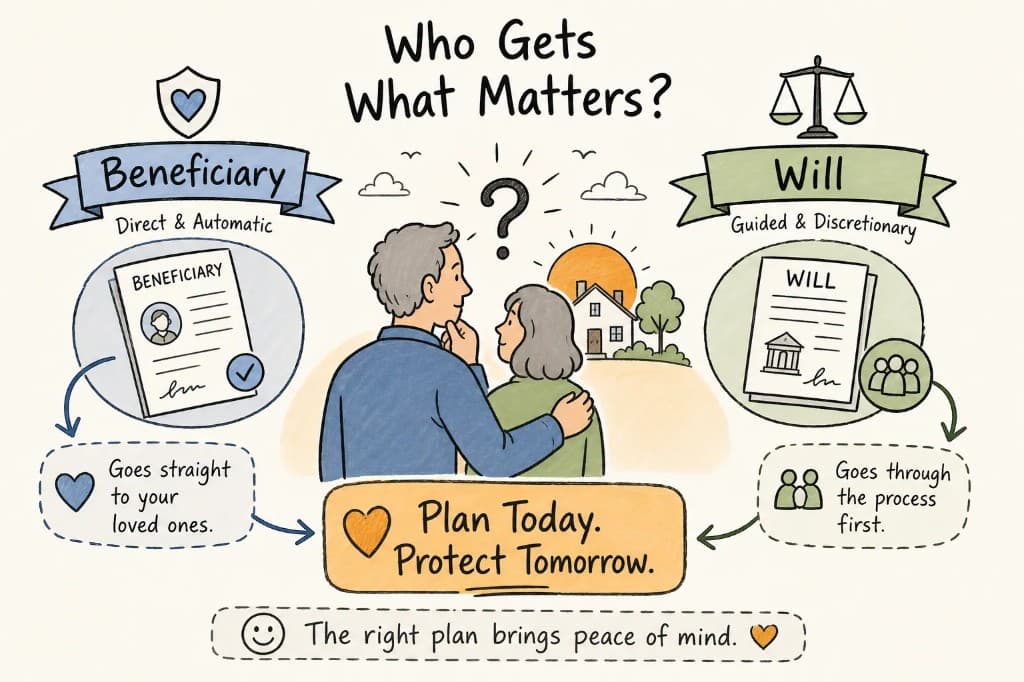
That beneficiary designation doesn't care what your will says. It doesn't go through your executor. It doesn't wait for probate. It just pays. This means if you named your ex-spouse on your RRSP fifteen years ago and never updated it, that form controls, regardless of what your will or your current relationship says.
This guide walks through exactly which assets each approach governs, what the tax and probate implications look like in practice, and how to make sure your designations and your will are working together. Getting this right before you sit down with a lawyer makes the whole conversation faster, cheaper, and far more productive.
Should you name a beneficiary or use your will in Canada?
Understanding the split
The foundational split in Canadian estate planning is between assets that transfer by contract and assets that transfer through your estate. Every decision about beneficiary designations and will instructions flows from understanding this distinction clearly.
Registered accounts, life insurance, and pensions: the direct transfer lane
RRSPs, RRIFs, TFSAs, life insurance policies, and most pension death benefits pass directly to the named beneficiary when a valid designation is on file. In most cases, these assets bypass your estate entirely. Your will generally has no authority over them, and your executor has no role in distributing them. The financial institution or insurer confirms the designation and pays the named beneficiary directly, often promptly, though timing varies by provider and complexity. Keep in mind that an invalid designation, a predeceased beneficiary with no contingent named, or a successful dependent support claim can change this outcome, so getting the details right matters.
This direct-transfer mechanic is one of the most powerful tools in estate planning, but only when it's used deliberately. A designation made at account opening and never revisited is not a plan. It's a default that may or may not reflect your current wishes.
Real estate and bank accounts: what typically goes through your estate
Real estate held in your name alone, personal bank accounts, non-registered investment accounts without designations, and most business interests pass through your estate and are distributed according to your will. If you die without a valid will, intestacy laws in your province determine who gets what, which may look nothing like what you intended. These are the assets where your will actually has authority, so making sure it exists and is current matters enormously for this category.
Joint tenancy with right of survivorship changes this picture for real estate. Property held jointly passes automatically to the surviving co-owner, outside the estate entirely, without a designation form required. This is worth understanding if you co-own property with a spouse or partner.
The estate-as-beneficiary trap
When no beneficiary is named on a registered account, or when the named beneficiary has predeceased you, the account typically falls back into your estate. That means it goes through probate, loses its direct-transfer advantage, and becomes exposed to creditors. Naming the estate as beneficiary intentionally has the same effect. This is an extremely common mistake, and one that requires nothing more than a form update to fix.
What beneficiary designations mean for probate in Canada
Probate is the court process that validates your will and authorizes your executor to act on behalf of the estate. It takes time, and in most provinces, it costs money based on the size of the estate. Assets that transfer by beneficiary designation are generally excluded from that calculation, though valid, direct-payable designations are the key; plan terms and provincial rules can affect what counts.
How removing assets from your estate lowers the probate bill
Assets with valid named beneficiaries are typically not counted in the probateable estate value. The financial institution confirms the designation, pays the beneficiary, and the court never sees that asset. On a large estate, this exclusion can represent significant savings, not just in fees, but in the time and administrative burden placed on your executor.
Ontario, BC, and Alberta: what the numbers actually look like
The fee structures vary dramatically by province, and the difference is worth knowing. As of 2026, Ontario charges nothing on the first $50,000, then $15 per $1,000 above that threshold, with no cap. On a $1 million estate, that's approximately $14,250 in probate fees alone. British Columbia uses a similar tiered structure with no cap, landing at roughly $13,500 to $13,650 on a $1 million estate. Alberta takes a completely different approach: a flat fee structure that caps at $525 regardless of estate size above $250,000. Confirm current figures with your provincial government or a legal advisor, as fee schedules can change.
What this means practically is that in Ontario and BC, keeping significant registered account balances out of the probateable estate through valid beneficiary designations can save thousands of dollars. Alberta residents face far less financial pressure on this front, though the other benefits of direct transfer still apply. Probate avoidance is not a strategy in itself; it's a natural benefit of naming beneficiaries deliberately.
The tax picture each path creates
Probate fees are only part of the story. The tax consequences of who inherits what, and through which path, can be far more significant than any court fee. This is where most Canadians need to pay close attention.
RRSP and RRIF at death: who actually owes CRA
At death, the Canada Revenue Agency includes the full fair market value of a deceased person's RRSP or RRIF as income on their final tax return. The beneficiary may receive the funds, but the estate is generally responsible for the resulting tax bill. This is a detail many Canadians miss entirely when they focus only on who receives the account. A beneficiary could receive $200,000 from an RRSP while the estate faces a tax liability in the same range, leaving less for everyone else.
The estate pays the tax, not the beneficiary directly, but that tax comes out of whatever is left in the estate. If the estate doesn't have sufficient liquid assets to cover it, the resulting imbalance can create real conflict among beneficiaries.
The spousal rollover and who qualifies
A surviving spouse or common-law partner can roll the RRSP or RRIF into their own registered account, deferring the tax until they make withdrawals. This is a significant tax-planning tool available to spouses and common-law partners under the Income Tax Act. Adult children, siblings, or any other beneficiaries do not qualify for this rollover as a general rule, they receive the funds after the tax is settled at the estate level. There is a limited exception under the Income Tax Act for financially dependent children or grandchildren in certain circumstances; a tax advisor or reference to CRA guidance can clarify whether that applies to your situation.
This distinction makes the choice of beneficiary on a registered account a meaningful tax decision, not just a distribution decision. Naming your spouse as primary beneficiary and an adult child as contingent beneficiary is a commonly recommended structure, primarily because of the spousal rollover tax deferral and to provide succession if the primary beneficiary predeceases you, but whether it's right for your situation depends on your family structure and overall plan. Talking through this with an advisor before you fill out the form is worthwhile.
TFSA and life insurance: the cleaner tax outcome
TFSAs and life insurance death benefits have a simpler tax picture. TFSA growth up to the date of death is generally tax-free to the named beneficiary. If your spouse is named as a successor holder rather than simply a beneficiary, the TFSA stays open in their name and continues to grow tax-sheltered without using any of their own contribution room. Life insurance proceeds paid to a named beneficiary are not included in the deceased's income and are received entirely tax-free. For these two asset types, keeping beneficiary designations current is especially important because the tax advantage only flows when the direct-transfer path is intact.
When a designation overrides your will in Canada
This is the legal hierarchy most Canadians don't encounter until an estate is already in dispute. Understanding it now prevents conflicts, contested estates, and unintended payouts to people you no longer intended to benefit.
Why the designation almost always wins
For registered plans and life insurance, a valid beneficiary designation takes legal precedence over conflicting will instructions. A general residual clause in a will, such as "I leave everything else to my spouse", does not override a designation naming someone else. The last valid designation on file with the institution is what controls. Provincial law may allow a will to revoke a designation, but only if it expressly identifies the specific account and meets the legal requirements set out in the applicable legislation. A general clause is not enough.
Divorce, remarriage, and the stale designation risk
Beneficiary designations are not automatically updated when your life changes. With limited exceptions, including rules in Quebec, where a spouse named as beneficiary on a life insurance policy is generally irrevocable under the Civil Code of Québec unless the designation states otherwise, a divorce does not erase an ex-spouse named on your RRSP or life insurance policy. Remarriage does not automatically add your new partner. If you named a parent as beneficiary on your life insurance twenty years ago and never updated the form, that parent receives the proceeds regardless of who your will names or who you've spent the last decade building a life with.
The practical implication is clear: beneficiary designations require active maintenance. Every major life event, marriage, separation, birth of a child, death of a named beneficiary, should trigger a review of every designation on file. A separation agreement or court order can require a change, but it does not automatically update the record at the institution. You have to file the new form yourself.
Seeing the real impact before you commit
Many Canadians make beneficiary decisions in isolation: at account opening, under time pressure, with no clear picture of how that single choice interacts with the rest of the estate. There's a better way to approach this before those decisions become permanent.
Why guessing at the outcome is the wrong move
Without modelling both scenarios side by side, it's nearly impossible to see how a beneficiary designation on an RRSP affects what your executor can distribute, how the tax owing on that account interacts with what remains in the estate, or whether one beneficiary ends up with a disproportionate share simply because of how assets are structured. These aren't edge cases reserved for large or complicated estates. They're the default result when planning happens piecemeal, account by account, without a complete picture.
How RiGEL lets you compare both paths before the lawyer meeting
There's a real gap between "I should probably figure this out" and "I'm sitting across from a lawyer", and that's the space RiGEL was built for. RiGEL is a Canadian estate planning platform currently in beta that brings your assets, beneficiaries, and planning decisions together in one place. Its Scenario Modelling feature is designed to help you compare how different designation choices affect each person's outcome side by side. The Beneficiary Planner gives you a clearer picture of who gets what under each approach, so you can see the full distribution before anything is finalized.
Going into a legal or financial consultation with that level of clarity saves time, reduces back-and-forth with advisors, and helps you ask better questions. RiGEL is designed specifically for Canada's tax and probate context, with support for blended families, common-law couples, cross-border households, and Indigenous families navigating reserve property and related tax considerations. It doesn't replace your lawyer or accountant. It makes the time you spend with them far more productive.
How to update beneficiary designations the right way
Knowing what to do is only useful if you know how to act on it. Here's the practical process for the most common account types Canadians need to update.
The process by account type
For RRSPs and TFSAs, contact your financial institution and complete a new beneficiary designation form. Many institutions now allow this online through account settings. The most recent valid form replaces all prior designations for that account, so submitting an updated form is usually straightforward.
For employer pensions and group retirement plans, use the plan's change form or online portal, and note that some plans require the existing beneficiary's consent if the designation has been made irrevocable under the plan terms.
For life insurance, submit a new beneficiary form to the insurer directly. Many insurers accept this online or by mail.
One critical point applies across all account types: beneficiary changes are not retroactive, and a separation agreement or divorce decree does not update your institutional records. The new form has to be filed directly with each institution, separately, for each account. There's no central registry that handles this for you.
Irrevocable designations and what they actually mean
An irrevocable beneficiary designation cannot be changed or removed without that person's written consent. This arrangement sometimes appears in separation agreements as a condition of support. In Quebec, the Civil Code generally makes a spouse named as beneficiary on a life insurance policy irrevocable by default unless the designation states otherwise, a province-specific rule that catches many people off guard. If you have an irrevocable designation on any account, you cannot update it unilaterally, regardless of how your circumstances have changed. Confirming the designation type with every institution during your review is a worthwhile step, because discovering an irrevocable designation you didn't know about after a major life change creates a genuinely difficult situation.
Coordinate both, and do it deliberately
The goal is not to choose between a beneficiary designation and a will. That's rarely the right frame. Both serve essential functions, and neither replaces the other. Beneficiary designations handle the direct-transfer assets: faster, often outside probate, with specific tax consequences that depend on the account type and who you name. Your will handles everything else and sets the rules for contingencies when designations fail, including when a named beneficiary predeceases you without a contingent beneficiary named to step in.
Three mistakes come up again and again in Canadian estates: leaving beneficiary designations stale after major life changes, failing to name a contingent beneficiary so accounts fall into the estate when the primary beneficiary is gone, and assuming the will covers everything when it legally controls far less than most people expect. Each of these is fixable right now, before a crisis forces the issue.
So if you're still weighing whether to name a beneficiary or rely on your will in Canada, start with a designation review across every registered account, pension, and insurance policy you hold. Then compare the scenarios so you can see what your beneficiaries actually receive under your current setup versus what you intend. See how RiGEL works, then bring that picture to your legal or financial advisor and have a real conversation instead of starting from scratch. The people who matter most deserve to receive exactly what you intend, not what a form you filled out years ago decided for you.